Quick Summary / AI Overview Snippet
Quick Answer: There is no direct free zone to mainland conversion uae authorities process as a simple licence swap — a free zone entity cannot be legally “converted” into a mainland LLC. Businesses actually choose between three routes: a mainland branch of free zone company structures (taxed at 9% on branch profit, parent stays 0% QFZP if conditions hold), a parallel mainland entity alongside the existing free zone company, or, for Dubai-based free zones specifically, a newer Mainland Operating Permit under Dubai Executive Council Resolution No. 11 of 2025 that lets qualifying free zone companies sell directly to mainland clients without a separate branch. Full migration — winding down the free zone company and starting fresh on mainland — is the fourth, most disruptive option, reserved for businesses whose model no longer fits a free zone at all.
Introduction
Search “free zone to mainland conversion” and most of what comes back describes a process that doesn’t actually exist: a clean licence swap where your free zone company simply becomes a mainland one. It doesn’t work that way, and believing it does is the first expensive misunderstanding founders run into once their free zone company outgrows what a free zone can offer.
The entire UAE business-setup content industry writes for people who haven’t set up yet — endless “mainland vs free zone” comparisons for first-time founders. Almost nobody writes for the thousands of companies that already set up in a cheap free zone, are now winning mainland clients they legally can’t invoice properly, and need to know what actually happens next. That’s the gap this guide fills.
There are genuinely three practical routes here, plus a regulatory development from 2025 that’s changed the calculus for Dubai-based free zone companies specifically. Each route carries a different cost, a different tax consequence, and — critically — a different risk to your existing Qualifying Free Zone Person status. Getting this choice wrong doesn’t just cost money; it can retroactively cost you the 0% tax position you built your entire structure around.
Why “Conversion” Is the Wrong Word
Before the routes themselves: understand that there is no direct conversion mechanism between a free zone entity and a mainland LLC in the UAE, in 2026, in either direction. A free zone company is licensed by its free zone authority under that authority’s own regulations; a mainland LLC is licensed by the DET (or the relevant emirate’s Department of Economic Development) under the federal Commercial Companies Law. These are structurally different legal frameworks, and no process transforms one into the other.
What actually happens when people say “convert” is one of two things: incorporating a new mainland entity and winding down the free zone company (a genuine migration, not a conversion), or adding mainland capability alongside the existing free zone company through a branch, permit, or parallel entity — while the free zone company continues to exist unchanged.
Expert Tip: This distinction matters practically, not just semantically. If your consultant or advisor describes a “conversion” as a quick licence amendment, that’s a signal to ask more questions. Every legitimate route here involves either a new legal entity/branch registration process or a genuine wind-down of the existing one — never a same-entity status change.
Can a Free Zone Company Do Business in Mainland Dubai?
The answer has changed meaningfully as of 2025, and this is the single most important update most competitor content on this topic hasn’t caught up to.
Historically: No, not directly. Free zone companies needed a local mainland distributor, a separately licensed mainland branch, or a dual-licence arrangement to invoice mainland customers.
As of Dubai Executive Council Resolution No. 11 of 2025: Qualifying Dubai free zone establishments can now apply for a Mainland Operating Permit through DET, authorising specified activities directly on the Dubai mainland — without necessarily requiring a full separate branch registration. This genuinely blurs what was previously a bright regulatory line, though only for Dubai-based free zones, and only for businesses that obtain and actively maintain the correct permit.
Important limitation: This resolution does not apply to companies licensed under the Dubai International Financial Centre (DIFC), which continues under its own distinct legal and regulatory framework. And outside Dubai — in Abu Dhabi, Sharjah, and other emirates — the traditional restriction still applies: a free zone company needs a branch, agency arrangement, or dual licence to trade locally.
Expert Tip: Industry observers widely expect FTA scrutiny of QFZP claims to intensify through 2026 as the corporate tax regime matures and more free zone companies test the boundaries of mainland activity. A permit that technically allows mainland sales doesn’t automatically preserve your 0% tax position on that income — those are two separate questions, addressed below.
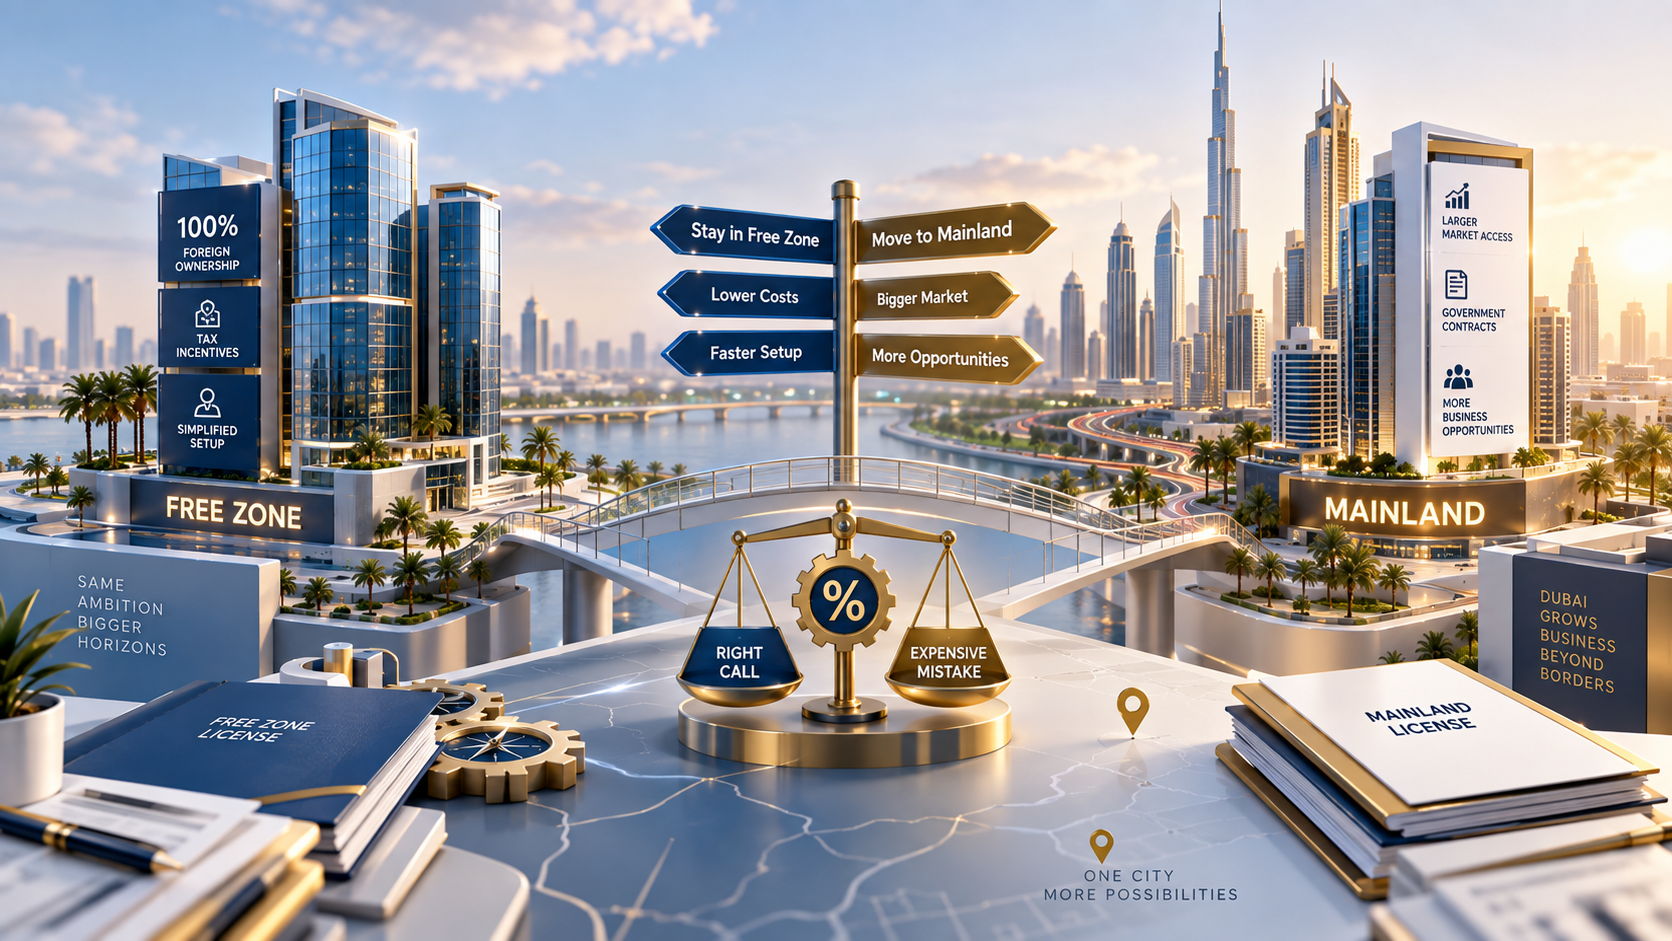
The Three Real Routes, Compared
| Factor | Route 1: Mainland Branch | Route 2: Parallel Mainland Entity | Route 3: Dubai Mainland Operating Permit |
|---|---|---|---|
| Structure | Branch of the existing free zone company, registered with DET | New, separate mainland LLC alongside the free zone company | Permit attached to the existing free zone licence — no new entity |
| Legal Entity Created? | No — it’s a branch, not a separate entity | Yes — fully separate legal entity | No |
| Where Available | Dubai and other emirates (via local DED) | Any emirate | Dubai only, and not for DIFC entities |
| QFZP Impact on Parent | Parent retains 0% on qualifying income if conditions met; branch profit taxed at 9% | Free zone parent unaffected; mainland entity taxed independently at 9% | Mainland income via permit is generally non-qualifying; must stay within de minimis or risk full QFZP loss |
| Office Requirement | Typically requires Ejari-registered mainland premises for a physical branch; remote/service-only branch licences may avoid this | Full mainland office/Ejari requirement, as with any new mainland LLC | Often permits remote operation from existing free zone premises for many activities |
| Government Contract Eligibility | Generally yes, via the branch | Yes, fully | Varies by activity and permit scope — confirm case by case |
| Relative Cost | Moderate | Highest (full new entity setup) | Lowest, where applicable |
| Best Suited For | Established free zone companies with steady, growing mainland demand | Businesses needing full mainland independence, government contracts, or planning eventual free zone exit | Dubai free zone companies wanting mainland revenue without new entity overhead |
Route 4: Full Migration (Wind Down and Start Fresh)
The most disruptive option — genuinely dissolving the free zone company and incorporating a new mainland entity — exists for businesses whose model no longer fits a free zone structure at all: predominantly mainland retail, activities requiring specific local regulatory licensing (certain legal, medical, or insurance activities), or businesses that have simply outgrown every advantage the free zone originally offered. This route involves full Company Closure Services for the free zone entity, a completely fresh UAE Mainland Business Setup process, and migration of contracts, banking, and visas — the most expensive and time-consuming route by a wide margin.
Mainland Branch of a Free Zone Company: How It Works
This is the most commonly used route for established free zone companies with genuine, growing mainland demand.
Step-by-Step: DET Branch Registration
- Confirm activity eligibility — the branch activity generally must align with or reasonably extend the parent free zone company’s licensed activities.
- Reserve a branch trade name — typically mirroring the parent company’s name, consistent with standard branch-naming conventions.
- Obtain DET initial approval for the branch registration.
- Prepare and attest parent company documents — trade licence, MOA, board resolution authorising the branch, and Power of Attorney for the branch manager.
- Secure mainland premises and Ejari registration — required for a physical branch licence; some activities qualify for remote or service-only branch arrangements that avoid this step.
- Submit the full application to DET and pay applicable registration and licensing fees.
- Receive the branch trade licence.
- Register the branch for Corporate Tax as a distinct taxable presence for its mainland-sourced income.
Expert Tip: A branch is not a separate legal entity — liability still flows back to the parent free zone company, exactly as with a foreign company’s branch. This is a structural nuance many founders overlook: adding mainland capability through a branch doesn’t create the liability separation a genuinely independent mainland LLC would.
Do I Lose 0% Tax If I Move to Mainland?
This is the question that should drive the entire decision, and the honest answer is: it depends entirely on which route you choose and how disciplined your accounting is afterward.
How QFZP Status Interacts With Each Route
Mainland Branch: The free zone parent’s qualifying income can continue at 0%, provided the parent still meets every QFZP condition independently. The branch’s own mainland-sourced profit is taxed at the standard 9% rate as a domestic permanent establishment — but critically, branch income does not itself disqualify the parent’s QFZP status, provided the two income streams are properly segregated.
Parallel Mainland Entity: Cleanest from a QFZP perspective. The free zone company continues entirely unaffected, since the mainland entity is a wholly separate taxpayer. This structural separation is precisely why many advisors recommend this route specifically to protect existing QFZP status.
Dubai Mainland Operating Permit: Here’s where real risk lives. Mainland income generated under this permit is generally treated as non-qualifying income for QFZP purposes. If that income stays within the de minimis threshold — the lower of AED 5,000,000 or 5% of total revenue — the parent’s QFZP status on its other qualifying income remains intact. Exceed that threshold, and the company risks losing QFZP status entirely, on all its income, not just the mainland portion.
The Mandatory Compliance Requirement Across All Routes
Regardless of which route you choose, the Federal Tax Authority requires clear segregation of financial records between free zone and mainland-sourced income, so qualifying and non-qualifying income can be independently verified. This isn’t optional bookkeeping hygiene — it’s the specific mechanism that allows a hybrid structure to retain any 0% tax position at all.
Expert Tip: SmartBiz.ae’s clearest advice here: if your mainland revenue is genuinely modest and likely to stay that way, a mainland branch or the Dubai operating permit — monitored quarterly against the de minimis threshold — is usually the more efficient route. If mainland revenue is set to become a significant or dominant part of your business, a parallel mainland entity protects your free zone QFZP position more cleanly and avoids the ongoing risk of a single strong quarter accidentally breaching the de minimis cap.
Is a Mainland Branch Better Than Converting?
Given that direct “conversion” doesn’t exist as a mechanism, the real comparison is branch vs. parallel entity vs. full migration — and the right answer depends on your growth trajectory, not a fixed rule.
A mainland branch tends to be the better fit when:
- Mainland demand is real but not yet dominant relative to your free zone/international business
- You want to preserve your existing QFZP structure with minimal disruption
- You don’t need full legal separation between the mainland and free zone operations
- Your activity qualifies for a remote or service-only branch licence, avoiding a second office lease
A parallel mainland entity tends to be the better fit when:
- You’re pursuing UAE government contracts, which generally require mainland licensing and are typically unavailable to free zone entities
- Mainland revenue is becoming a primary, not secondary, part of the business
- You want clean liability separation between mainland and free zone operations
- Your free zone company’s QFZP position is financially significant enough to justify the extra setup cost of full separation
Full migration tends to be the right (if disruptive) call when:
- Your activity now requires local licensing your free zone structure can never satisfy (certain retail, legal, medical, or Central Bank–regulated activities)
- Free zone advantages — 0% qualifying income, 100% ownership — no longer meaningfully apply to how the business actually operates
- The administrative overhead of maintaining two structures outweighs the benefit of keeping the free zone entity alive
Practical Considerations Beyond Tax
Tax treatment is the headline issue, but several operational factors matter just as much in choosing the right route.
Existing Visa Transfer
Employees currently sponsored under the free zone company’s establishment card don’t automatically transfer to a new mainland branch or entity. A mainland branch generally requires its own establishment card and visa quota, meaning existing staff visas need re-processing under the new structure — a cost and timeline factor often underestimated in planning.
Ejari and Office Requirement
A physical mainland branch typically requires Ejari-registered premises separate from any free zone facility. Some Dubai Mainland Operating Permit activities avoid this by allowing operation from existing free zone premises — making the permit route meaningfully cheaper for service-based businesses that don’t need a mainland storefront or warehouse.
Licence Cancellation vs. Conversion
If pursuing full migration rather than a branch or parallel structure, proper licence cancellation of the free zone entity — rather than simply letting it lapse — protects against lingering liability, unresolved fines, or complications with future UAE business activity. This should route through formal Company Closure Services and, where the entity had meaningful financial activity, a proper Company Liquidation Report, rather than an informal wind-down.
Multi-Emirate Complexity
Each emirate issues its own commercial licensing independently. A Dubai Mainland Operating Permit authorises mainland activity within Dubai only — it does not extend to Abu Dhabi, Sharjah, or other emirates. A business needing mainland presence across multiple emirates needs separate permits or entities in each, following that emirate’s specific Department of Economic Development requirements.
Real Estate, Banking and Compliance Implications
Adding mainland capability, in any form, touches nearly every part of a company’s operational infrastructure, not just its licensing.
Banking: A new mainland branch or entity typically requires its own Bank Account Opening Support process — banks generally treat a branch or new entity as a fresh KYC case, even where the parent company already banks with the same institution.
Tax Registration: Both structures need independent attention to Corporate Tax Registration and ongoing Corporate Tax Filing, given that mainland-sourced income is assessed and reported separately from qualifying free zone income under the segregation requirement described above.
VAT: Where mainland activity crosses the VAT threshold independently, or interacts with existing VAT Registration, ongoing VAT Filing & Return Services need to reflect the correct entity and income attribution across both structures.
Audit Readiness: Given the FTA’s segregation requirement between qualifying and non-qualifying income, clean Company Audit Reports become genuinely load-bearing for a hybrid structure — not just an annual formality, but the actual evidence that protects your QFZP position if the FTA reviews it.
Given how many moving parts a mainland expansion touches — branch registration, Ejari, visa re-processing, banking, and dual tax reporting — most established free zone companies pursuing this route rely on coordinated PRO Services UAE support rather than managing each workstream separately. A Business Services Hub relationship that already understands your free zone company’s structure is generally better positioned to manage the transition cleanly than starting fresh with a new provider for the mainland side alone.
Common Mistakes Businesses Make When Expanding to Mainland
- Assuming “conversion” is a simple licence swap — no such direct mechanism exists; every route involves either a new branch/entity or a genuine wind-down.
- Adding mainland revenue without segregating financial records — the single fastest way to jeopardize QFZP status even where the underlying structure was chosen correctly.
- Not monitoring the de minimis threshold quarterly — a business growing mainland revenue under a permit or branch can drift past the threshold without anyone actively tracking the ratio.
- Assuming the Dubai Mainland Operating Permit applies everywhere — it’s Dubai-specific and excludes DIFC entities entirely; other emirates still require the traditional branch or distributor route.
- Underestimating visa re-processing costs — existing staff visas don’t automatically carry over to a new mainland branch or entity.
- Choosing a parallel entity when a branch would have sufficed — incurring full second-entity setup costs for a business whose mainland revenue never justified that level of structural separation.
- Letting the free zone entity lapse informally during a full migration — rather than properly closing it, risking fines and future compliance flags.
FAQ: Free Zone to Mainland Expansion
Q1: Can a free zone company do business in mainland Dubai? Yes, through a mainland branch, a parallel mainland LLC, or — for qualifying Dubai free zone companies since Dubai Executive Council Resolution No. 11 of 2025 — a Mainland Operating Permit attached to the existing free zone licence. Direct free zone-to-mainland sales without one of these mechanisms are generally not permitted.
Q2: How do I convert my free zone company to mainland? There is no direct conversion mechanism. Businesses either add mainland capability alongside the existing free zone company (via a branch, parallel entity, or permit) or wind down the free zone company entirely and incorporate a fresh mainland entity.
Q3: Do I lose 0% tax if I move to mainland? Not necessarily. A properly structured mainland branch or parallel entity, with financial records correctly segregated between qualifying and non-qualifying income, can preserve the free zone parent’s QFZP status. Risk arises specifically when non-qualifying mainland income exceeds the de minimis threshold — the lower of AED 5,000,000 or 5% of total revenue.
Q4: Is a mainland branch better than converting? Since direct conversion doesn’t exist, the real comparison is branch vs. parallel entity vs. full migration. A branch suits moderate, growing mainland demand with minimal disruption; a parallel entity suits businesses needing government contract eligibility or full liability separation; full migration suits businesses whose model no longer fits a free zone structure at all.
Q5: Does the Dubai Mainland Operating Permit work in other emirates? No. It applies specifically to Dubai, under Dubai Executive Council Resolution No. 11 of 2025, and does not apply to DIFC-licensed entities. Free zone companies in Abu Dhabi, Sharjah, and other emirates still need a traditional branch, agency arrangement, or dual licence to trade on the mainland in those jurisdictions.