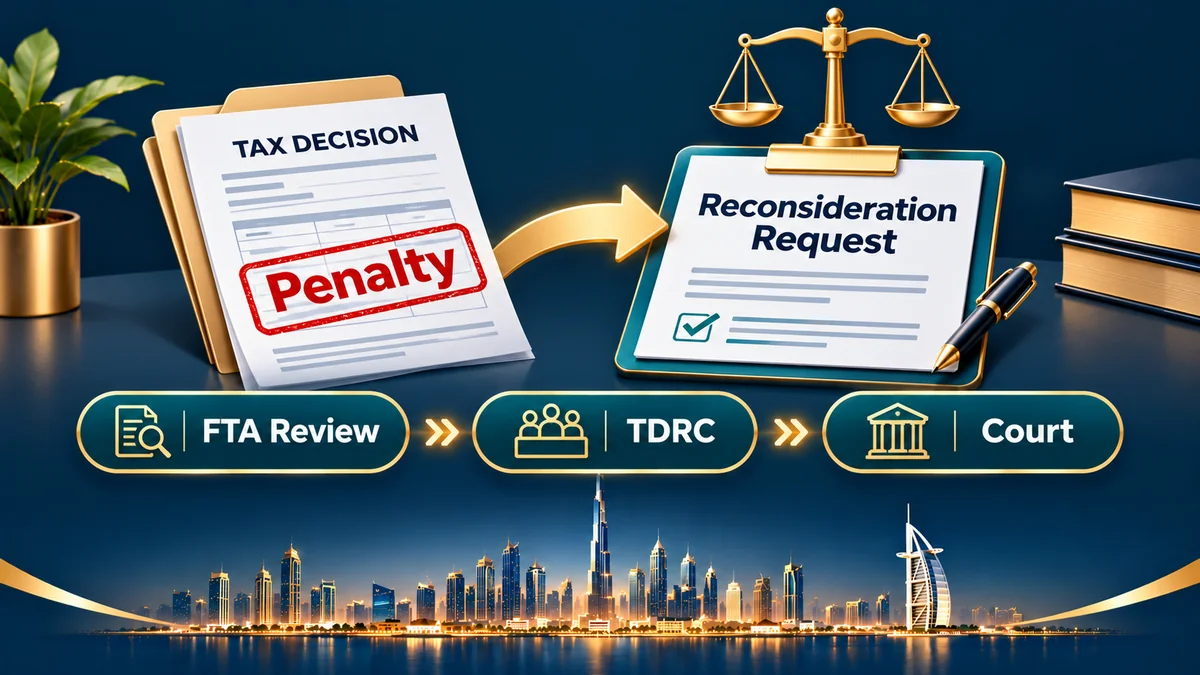
Quick Answer: An FTA reconsideration request is the first formal step to challenge an FTA decision in the UAE, such as an administrative penalty, a tax assessment or a rejected refund or registration. It is submitted on EmaraTax within 40 business days of being notified of the decision. It is free of charge and must be supported by factual and legal grounds with documentary evidence. The FTA may take up to 45 business days to decide, and can extend this. If the outcome is unfavourable, or the FTA does not respond in time, the next step is an objection to the Tax Disputes Resolution Committee (TDRC), followed by the federal courts for larger disputes.
Receiving a penalty notice or a tax assessment from the Federal Tax Authority can feel final. It is not. UAE tax law gives every taxpayer a structured right to ask the FTA to review its own decision, and many penalties are reduced or cancelled at this stage when the taxpayer presents a clear, well-documented case.
This guide explains the FTA reconsideration process step by step: which decisions can be challenged, the deadlines that apply, how to prepare strong grounds, how to file an EmaraTax reconsideration, and what to do if the FTA does not accept your request.
FTA Reconsideration UAE: Key Numbers at a Glance
| Figure | What it means |
|---|---|
| 40 business days | Deadline to submit a reconsideration request after being notified of the FTA decision |
| 45 business days | Time the FTA may take to decide on a complete request (extendable) |
| AED 0 | Fee for submitting a reconsideration request |
| 40 business days | Deadline to object to the Tax Disputes Resolution Committee after the reconsideration decision |
| 20 + 20 business days | TDRC decision period, extendable once |
| AED 100,000 | Disputes at or below this amount end at the TDRC; above it, a court appeal is possible |
| 5 MB | Maximum size per supporting document on EmaraTax |
What Is an FTA Reconsideration Request?
An FTA reconsideration request is a formal application asking the Federal Tax Authority to review and change a decision it has issued to you. It is governed by the Tax Procedures Law (Federal Decree-Law No. 28 of 2022, as amended) and applies across UAE taxes, including Corporate Tax, VAT and Excise Tax.
It is the mandatory first stage of any UAE tax dispute. You cannot go directly to the Tax Disputes Resolution Committee or the courts without first asking the FTA to reconsider.
Reconsideration is not the same as a voluntary disclosure. A voluntary disclosure corrects your own tax return. A reconsideration request challenges a decision the FTA has made about you.
Which FTA Decisions Can Be Challenged?
Only official FTA decisions that concern you can be reconsidered. General inquiries, complaints and clarification requests are handled through other channels.
| Can be reconsidered | Cannot be reconsidered through this route |
|---|---|
| Administrative penalties (late registration, late filing, late payment, record-keeping) | General inquiries or complaints |
| Tax assessments issued after an FTA audit | Requests for clarification on how the law applies |
| Rejection of a refund application | Errors in your own return (use a voluntary disclosure instead) |
| Rejection or cancellation of tax registration or deregistration | Decisions that do not relate to you |
| Decisions on tax group applications | |
| Other formal FTA decisions affecting your tax position |
Reconsideration vs Other Options: Which Route Fits Your Case?
| Route | Use it when | Decided by | Typical timeframe |
|---|---|---|---|
| Voluntary disclosure | You found an error in your own return | FTA | Processed after submission |
| Reconsideration request | You disagree with an FTA decision, assessment or penalty | FTA | Up to 45 business days (extendable) |
| Penalty waiver or instalment request | You accept the penalty is valid but want it waived or paid in instalments | FTA Committee | Up to 110 business days |
| TDRC objection | Reconsideration was rejected or not answered in time | Tax Disputes Resolution Committee | 20 business days, extendable by 20 |
| Court appeal | The TDRC decision is unfavourable and the amount exceeds AED 100,000 | Federal courts | Often 12 to 24 months through all stages |
Strategic point: A reconsideration argues that the decision is wrong. A penalty waiver request accepts that the penalty applies but asks for relief, under Cabinet Decision No. 105 of 2021. Choosing the right route matters, and in some cases both can be relevant.
FTA Reconsideration Deadline: The 40 Business Day Rule
The single most important rule: submit your FTA reconsideration request within 40 business days of being notified of the decision.
- The clock starts from the date of notification, usually when the decision appears on EmaraTax or is emailed.
- Business days exclude weekends and official UAE public holidays.
- If you genuinely cannot meet the deadline, you may request an extension under FTA Decision No. 1 of 2025. Extensions are assessed against set conditions and are not automatic.
- If you have a tax assessment review request pending, you must wait for that decision, or for its deadline to pass, before filing a reconsideration on the same matter.
Missed the deadline? If no extension is granted, the decision generally becomes final, and you lose the right to escalate to the TDRC. Put the deadline in your calendar the day the decision arrives.
Visual: Full UAE tax dispute timeline
| Stage | Deadline / timeframe |
|---|---|
| 1. FTA decision issued | Day 0: notification date |
| 2. Submit reconsideration request | Within 40 business days |
| 3. FTA reviews and decides | Up to 45 business days (extendable) |
| 4. Object to the TDRC | Within 40 business days of the reconsideration decision (or of the FTA’s deadline passing without a decision) |
| 5. TDRC decides | 20 business days, extendable by a further 20 |
| 6. Appeal to the Federal Court of First Instance | Within 20 business days of the TDRC decision (only where the amount exceeds AED 100,000) |
| 7. Further appeals | Federal Court of Appeal, then the Federal Supreme Court |
Strong Grounds for an FTA Reconsideration Request
The FTA reviews requests on their merits and evidence. A request that simply says a penalty is “unfair” rarely succeeds. Stronger grounds include:
| Ground | Example | Evidence that helps |
|---|---|---|
| Factual error by the FTA | Penalty raised for a period when the business was already deregistered | Deregistration approval, licence cancellation documents |
| Incorrect application of the law | Corporate Tax charged on income that qualifies as exempt, or VAT at 5% on a zero-rated export | Contracts, export documents, legal references |
| Wrong amount or period | Penalty calculated on the wrong tax period or wrong tax difference | Filed returns, payment confirmations, ledgers |
| Compliance was actually met | Return or payment made on time but not recorded correctly | EmaraTax submission receipts, bank transfer proof |
| Circumstances beyond your control | Documented system outage or serious emergency preventing timely compliance | Screenshots, official notices, medical or incident records |
| Procedural irregularity | Required notifications not issued correctly | Correspondence history, notification records |
Weak grounds to avoid: “We were busy,” “our accountant left,” “we did not know the rule” or “the penalty is too high” without a legal basis. These rarely persuade the FTA.
How to File an EmaraTax Reconsideration: Step by Step
- Read the decision carefully. Note the decision reference number, the tax type, the period, the amount and the notification date.
- Calculate your deadline. Count 40 business days from the notification date.
- Identify your grounds. Decide whether the issue is factual, legal, procedural or circumstantial. Your request should rest on one or more clear grounds.
- Gather evidence. Collect returns, receipts, contracts, invoices, bank statements, correspondence and legal references.
- Draft your request. Explain what decision you are challenging, why it is incorrect and what outcome you are asking for. The FTA generally requires the request itself to be written in Arabic. Supporting documents may be in English.
- Log in to EmaraTax. Open the relevant Taxable Person profile, go to Other Services, then Reconsiderations, then New Request.
- Complete the form and upload documents. Accepted formats include PDF, Word, Excel, JPG and PNG, with a 5 MB limit per file.
- Submit and save the confirmation. Keep the reference number and monitor EmaraTax and email for FTA queries or the decision.
Who can submit: the taxpayer itself, a registered Tax Agent, a legal representative or, for a tax group, the representative member. Tax advisers who are not registered as Tax Agents cannot submit on a client’s behalf.
What Documents Support a Reconsideration Request?
| Document | Purpose |
|---|---|
| Copy of the FTA decision | Identifies exactly what is being challenged |
| Written grounds (in Arabic) | Sets out the factual and legal argument |
| Tax returns and EmaraTax receipts | Proves what was filed and when |
| Payment confirmations | Proves tax or penalties were paid on time |
| Contracts, invoices and export documents | Supports the correct tax treatment of transactions |
| Financial statements and ledgers | Supports corrected figures |
| Correspondence with the FTA | Shows communication history and notifications |
| Evidence of exceptional circumstances | Supports claims of events beyond your control |
| Tax advice received | The FTA asks for any relevant tax advice obtained |
Reliable books make every dispute easier to win. Professional accounting and bookkeeping ensures the evidence exists when you need it.
What Happens After You Submit?
The FTA can reach one of three outcomes:
| Outcome | What it means | Your next step |
|---|---|---|
| Accepted | The decision is cancelled or amended in full | Check that EmaraTax balances are updated |
| Partially accepted | The penalty or assessment is reduced | Decide whether to accept the reduced amount or escalate to the TDRC |
| Rejected | The original decision stands | Consider a TDRC objection within 40 business days |
What if the FTA does not respond to your reconsideration?
If the FTA does not issue a decision within its response period, including any extension, your request can be treated as rejected. You can then object to the TDRC within 40 business days of the date the FTA’s deadline expired.
Escalating a UAE Tax Dispute: The Tax Disputes Resolution Committee
If reconsideration does not resolve the matter, the next stage is the Tax Disputes Resolution Committee (TDRC).
- Who sits on it: A TDRC is chaired by a judge and includes tax experts. It operates under the judicial system, independently of the FTA.
- Deadline: File the objection within 40 business days of the reconsideration decision.
- Payment condition: The disputed tax and penalties must generally be paid before the TDRC will accept the objection. If you succeed, the amounts are refunded.
- Decision period: The TDRC decides within 20 business days, extendable by a further 20 business days.
- Finality: If the disputed amount is AED 100,000 or less, the TDRC decision is final.
Appealing to the UAE Courts
Where the disputed amount exceeds AED 100,000, a TDRC decision can be appealed to the Federal Court of First Instance, generally within 20 business days. Further appeals can go to the Federal Court of Appeal and then the Federal Supreme Court, whose decision is final. Court proceedings can take 12 to 24 months in total, so they are generally only practical for high-value disputes.
Penalty Waiver and Instalments: An Alternative to Reconsideration
Sometimes a penalty is legally correct, but paying it in full immediately is difficult, or there are strong grounds for relief. In that case, the FTA’s separate penalty waiver and instalment service may be more suitable:
| Feature | Penalty waiver / instalment request |
|---|---|
| Legal basis | Cabinet Decision No. 105 of 2021 |
| Who decides | FTA committee |
| Fee | Free |
| Decision time | Up to 110 business days |
| Instalment eligibility | Unsettled penalties of at least AED 50,000; no outstanding payable tax for the period |
| Undertakings required | To pay as agreed, and that the violation has been corrected and will not be repeated |
An objection through reconsideration does not prevent a penalty from later qualifying for an instalment plan.
Common Mistakes in FTA Reconsideration Requests
- Missing the 40 business day deadline. This is the most common and most costly mistake.
- Arguing fairness instead of law and facts. Emotional arguments without legal grounds rarely succeed.
- No supporting evidence. Claims without documents are easy to reject.
- Using the wrong route. Correcting your own return requires a voluntary disclosure, not a reconsideration.
- Not fixing the underlying problem. The FTA expects the compliance failure behind a penalty to be corrected.
- Ignoring partial acceptance options. A partial win may be the commercially sensible outcome.
- Not preparing for the TDRC payment condition. Escalation usually requires paying the disputed amounts first.
FTA Reconsideration Checklist
| Step | Done? |
|---|---|
| FTA decision reference and notification date recorded | ☐ |
| 40 business day deadline calculated and diarised | ☐ |
| Grounds identified (factual, legal, procedural or circumstantial) | ☐ |
| Supporting documents collected and under 5 MB each | ☐ |
| Request drafted in Arabic | ☐ |
| Filed on EmaraTax by an authorised person | ☐ |
| Confirmation number saved | ☐ |
| Underlying compliance issue corrected | ☐ |
| Escalation plan (TDRC or waiver) considered | ☐ |
How SmartBiz Helps With FTA Penalties and Disputes
Most FTA penalties come from avoidable compliance gaps: late registration, late filing or weak records. SmartBiz helps UAE businesses prevent them and respond when they happen:
- VAT registration and VAT filing: on-time registration and accurate returns
- Accounting and bookkeeping in Dubai: the records you need to defend your position
- Business PRO services: support with government-facing processes and documentation
- Business setup in Dubai and company formation in the UAE, with tax compliance planned from day one
- A single point of contact through our business services hub in Dubai
Received an FTA penalty or assessment you disagree with?
SmartBiz helps you review the decision, assess your grounds and prepare a well-documented reconsideration request before the deadline. Book a Consultation
Frequently Asked Questions
What is an FTA reconsideration request in the UAE?
It is a formal request asking the Federal Tax Authority to review and change a decision it has issued to you, such as a penalty, tax assessment or refund rejection. It is submitted through EmaraTax and is the first step in any UAE tax dispute.
What is the deadline for an FTA reconsideration request?
You must submit the request within 40 business days of being notified of the FTA decision. An extension may be requested under FTA Decision No. 1 of 2025, but it is not automatic.
Is there a fee for an FTA reconsideration request?
No. Submitting a reconsideration request through EmaraTax is free of charge.
How long does the FTA take to decide a reconsideration request?
The FTA may take up to 45 business days from receipt of a complete request, and this period can be extended.
What happens if the FTA does not respond to my reconsideration request?
If the FTA does not decide within its response period, the request can be treated as rejected. You can then object to the Tax Disputes Resolution Committee within 40 business days.
Do I need to pay the penalty before filing a reconsideration request?
No. Payment is not required to file a reconsideration request. However, disputed taxes and penalties generally must be paid before an objection is accepted by the Tax Disputes Resolution Committee.
Can I go to court against an FTA decision?
Yes, but only after reconsideration and a TDRC objection, and only where the disputed amount exceeds AED 100,000. Disputes of AED 100,000 or less end with the TDRC decision.
What is the difference between reconsideration and a penalty waiver request?
A reconsideration argues that the FTA’s decision is wrong. A penalty waiver or instalment request accepts that the penalty applies but asks for relief or a payment plan.
Sources and Legal References
- Federal Decree-Law No. 28 of 2022 on Tax Procedures, as amended by Federal Decree-Law No. 17 of 2025
- FTA Decision No. 1 of 2025 on extension of the reconsideration deadline
- Cabinet Decision No. 105 of 2021 on instalment and waiver of administrative penalties
- Cabinet Decision No. 75 of 2023 on Corporate Tax administrative penalties
- Federal Tax Authority: Reconsideration Request service and Penalty Waiver and Instalment service, tax.gov.ae
Disclaimer: This article provides general information based on UAE tax legislation and FTA guidance available at the time of writing. It is not legal or tax advice. Dispute procedures, deadlines and thresholds can change, so confirm your specific position with a qualified tax adviser or registered Tax Agent before acting.