Setting up a company in the United Arab Emirates is an important milestone, but receiving a trade licence is not the final step in building a fully operational business. Once the company is registered, business owners may still need to arrange immigration formalities, open a corporate bank account, assess tax registration requirements, organise accounting records, and establish ongoing compliance procedures.
The exact next steps depend on the company’s legal structure, licensing authority, business activity, employees, and operational requirements. A mainland company may follow different procedures from a free zone company, while businesses operating in regulated sectors may need additional approvals before starting certain activities.
Understanding what to do after company formation in the UAE helps business owners prioritise essential tasks, avoid preventable delays, and establish a more organised foundation for growth.
This guide provides a practical post-incorporation checklist covering the steps to consider after receiving a UAE trade licence, the documents to organise, and the ongoing obligations that may apply to a newly established business.
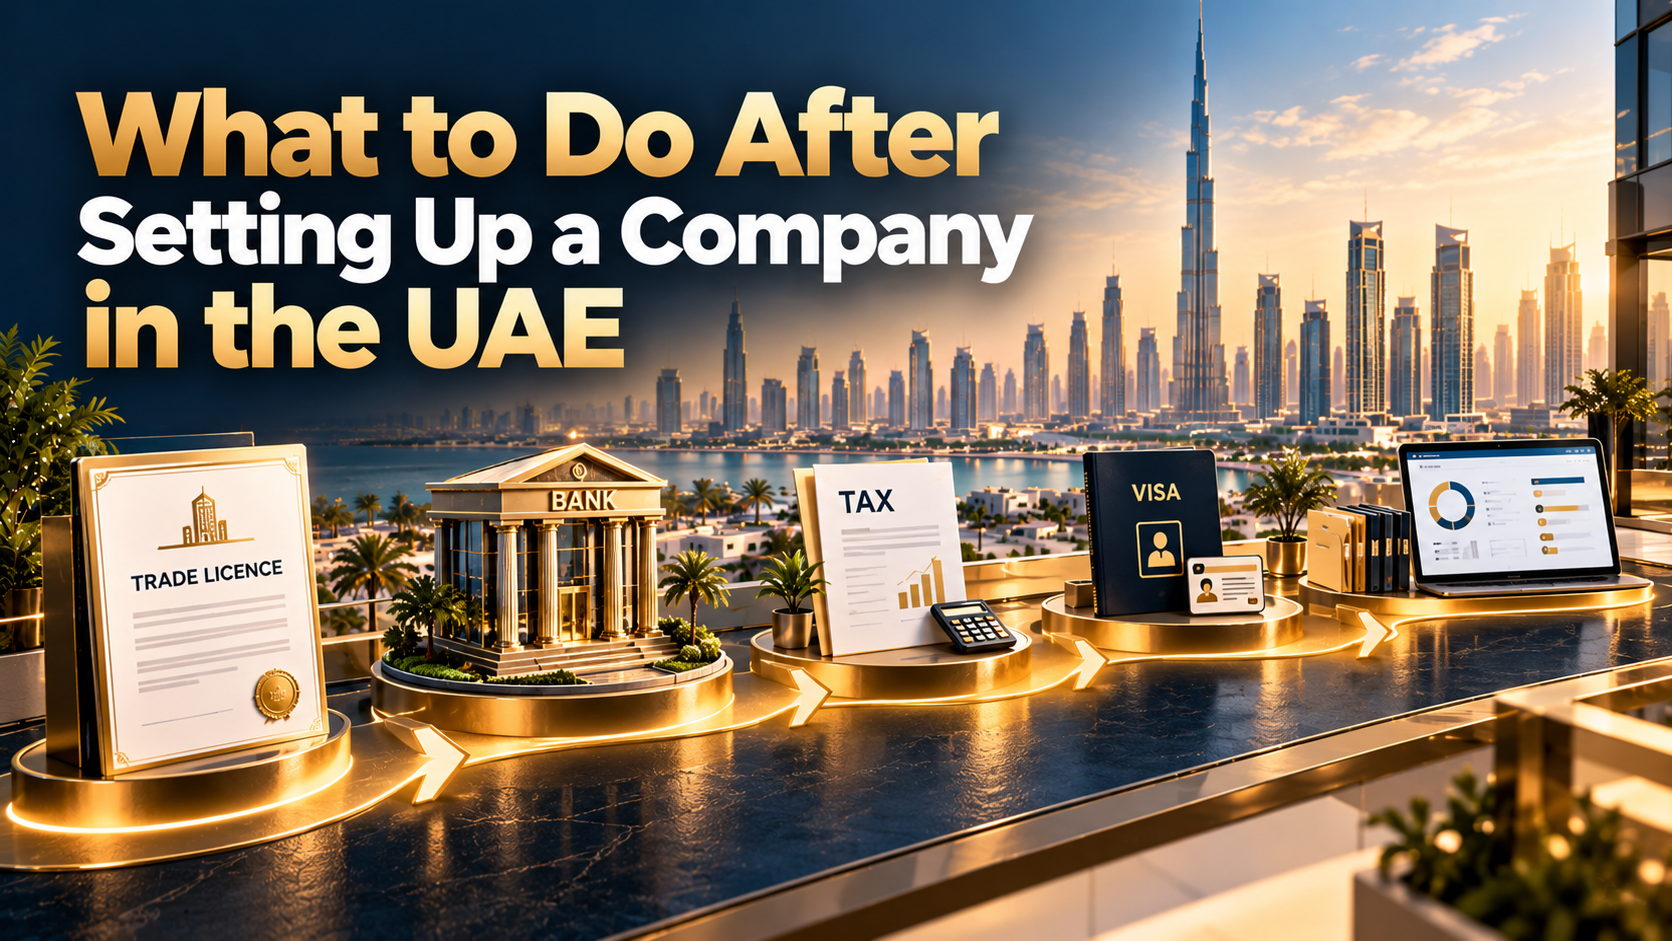
Quick Answer: What Should You Do After Company Formation in the UAE?
After registering a company in the UAE, business owners should review the following steps according to their circumstances:
- Collect and verify the company’s incorporation documents and trade licence.
- Confirm that the licensed activities and operational approvals match the intended business.
- Arrange establishment, immigration, and visa procedures where required.
- Prepare the documentation needed for a corporate bank account application.
- Assess Corporate Tax registration and filing obligations.
- Determine whether VAT registration is required.
- Set up accounting, bookkeeping, invoicing, and financial recordkeeping.
- Establish applicable employment, payroll, and workplace procedures.
- Review beneficial ownership and other corporate compliance requirements.
- Organise contracts, business insurance, operational systems, and supplier arrangements.
- Create a calendar for licence renewals, tax deadlines, and other recurring obligations.
Not every company needs to complete every item immediately. The appropriate sequence depends on the company’s activities, authority, workforce, and legal obligations.
1. Collect and Organise Your Company Documents
The first step after incorporation is to make sure that all issued company documents have been received, checked, and stored securely.
These records establish the company’s registration details and may be requested during banking applications, tax registration, immigration procedures, commercial transactions, and future licensing changes.
Documents to keep accessible
Depending on the company structure and registration authority, these may include:
- Valid trade licence.
- Certificate of incorporation or registration, where issued.
- Memorandum of Association (MOA) and Articles of Association (AOA), where applicable.
- Shareholder or partner information.
- Manager or director appointment documents.
- Lease, flexi-desk, or facility agreement, where applicable.
- Relevant approvals and permits.
- Establishment or immigration-related records, where applicable.
- Copies of submissions and official confirmations.
Check that the company name, legal form, shareholders, manager details, and licensed activities are accurate.
If any information is incorrect, contact the relevant authority to determine the appropriate correction procedure.
Create a central digital folder with controlled access and clear file names. Keep backup copies and ensure that authorised staff can locate essential documents when needed.
2. Confirm That Your Business Is Ready to Operate
A trade licence confirms the authorised activities under the applicable licensing framework, but it does not automatically mean that every operational requirement has been completed.
Before commencing commercial activities, check whether your business needs additional approvals, registrations, premises arrangements, or sector-specific permits.
Review your operational requirements
- Confirm that the intended activity matches the licence.
- Check whether additional government or regulatory approvals are required.
- Verify that the premises or workspace arrangement meets applicable conditions.
- Review any professional qualifications or sector-specific permits.
- Check whether your business model requires additional operational permissions.
- Confirm any conditions attached to the licence or relevant approvals.
For example, certain professional, technical, or regulated activities may require additional approvals before the company can legally provide the relevant services.
Business owners should not assume that an approval for one activity automatically covers every related service they plan to offer.
If you are still reviewing the appropriate licensing route or business structure, SmartBiz provides business setup support in Dubai.
3. Complete Establishment and Immigration Procedures Where Required
Depending on the registration authority and the company’s plans, additional immigration or establishment procedures may be necessary before the business can sponsor employees or apply for residence visas.
These procedures are separate from simply receiving a trade licence.
What should you check?
- Whether the company needs an establishment or immigration file.
- Which immigration authority handles the relevant application.
- Whether the company has an eligible visa allocation or quota.
- Which documents are required for the owner, manager, or employees.
- Whether a medical fitness examination and Emirates ID application are required for the relevant visa category.
- Whether health insurance or other requirements apply.
- How visa and permit expiry dates will be tracked.
The exact process depends on the company type, jurisdiction, and the immigration rules applicable to the applicant.
A company owner should not assume that every company receives the same number of visas or that visa eligibility is determined by the trade licence alone.
Prioritise visas according to business needs
If the owner intends to live in the UAE, check the applicable residence visa route and requirements.
If the company plans to recruit staff, determine the relevant employer registration, work permit, employment contract, and immigration procedures before onboarding employees.
Keep immigration records organised and monitor expiry dates to reduce the risk of missed renewals.
4. Prepare to Open a Corporate Bank Account
A corporate bank account is an important operational requirement for many businesses. It allows the company to receive commercial payments, pay suppliers, manage operating expenses, and maintain a clearer separation between personal and business finances.
However, company registration does not guarantee corporate bank account approval.
Banks apply their own onboarding, customer due diligence, risk assessment, and document requirements.
Common documents banks may request
Depending on the bank and the company’s circumstances, the application may require:
- Valid trade licence.
- Certificate of incorporation, where applicable.
- MOA or AOA.
- Passport and identification documents of shareholders and authorised signatories.
- Beneficial ownership information.
- Company address and contact details.
- Business plan or description of expected activities.
- Contracts, invoices, supplier information, or evidence of business activity.
- Expected transaction volumes and geographic markets.
- Source-of-funds information, where requested.
- Board resolutions or authorised-signatory documents, where applicable.
This is not a universal bank checklist. The bank may request additional documents based on the company’s ownership, activities, jurisdictions, or risk profile.
How to prepare for the application
First, make sure the information provided to the bank is consistent with the trade licence and incorporation documents.
Second, prepare a clear explanation of the company’s business model, expected customers, suppliers, transaction patterns, and funding arrangements.
Third, ensure that the relevant shareholders and authorised signatories are available to complete the bank’s verification process.
Avoid submitting incomplete or inconsistent information. If the bank requests clarification, respond with accurate supporting documents.
5. Assess Your UAE Corporate Tax Registration Obligations
Corporate Tax registration is an important post-incorporation consideration for businesses within the scope of the UAE Corporate Tax regime.
New company owners should assess their tax status early instead of waiting until the first financial year has ended.
The exact obligations depend on the company’s legal status, applicable tax rules, and any relevant exemptions or special treatment.
Corporate Tax checklist
- Determine whether the company is a taxable person under the applicable rules.
- Confirm whether Corporate Tax registration is required.
- Identify the applicable registration deadline.
- Determine the company’s tax period.
- Establish a reliable bookkeeping process.
- Maintain records supporting income, expenses, and tax calculations.
- Identify applicable return filing and payment deadlines.
- Review any special tax treatment or elections relevant to the company.
Under the general UAE Corporate Tax framework, taxable persons must generally file their return and pay the tax due within nine months from the end of the relevant tax period, subject to applicable rules and exceptions.
Corporate Tax registration deadlines can differ according to the type of taxable person and the relevant circumstances. Business owners should verify the deadline applicable to their company.
Free zone businesses should not assume that free zone registration automatically entitles them to the 0% Corporate Tax rate. Qualifying treatment depends on meeting the applicable conditions and requirements.
For official information, consult the Federal Tax Authority’s Corporate Tax legislation and guidance.
6. Determine Whether VAT Registration Is Required
VAT registration is another important consideration after company formation.
A newly established company should assess its taxable supplies, imports, and expected turnover to determine whether registration is mandatory or whether voluntary registration may be available.
The timing of the assessment matters because the relevant rules consider previous-period figures and, in specified circumstances, expectations about the next 30 days.
VAT checklist
- Assess whether the business makes taxable supplies.
- Monitor taxable turnover and relevant imports.
- Check the mandatory registration threshold.
- Assess voluntary registration eligibility.
- Register with the Federal Tax Authority when required.
- Configure invoices and accounting records appropriately.
- Establish a process for filing VAT returns and paying VAT due.
- Retain supporting documentation.
For UAE-resident businesses, the standard mandatory VAT registration threshold is generally AED 375,000 in taxable supplies and imports over the previous 12 months, or an expectation that the threshold will be exceeded within the next 30 days, subject to applicable rules.
The standard voluntary registration threshold is generally AED 187,500, subject to the relevant eligibility conditions.
Non-resident businesses may be subject to different rules. Businesses should confirm their status using current FTA guidance.
A newly formed company does not necessarily need to register for VAT immediately. The decision depends on its circumstances and the applicable rules.
Official reference: Federal Tax Authority — VAT returns and payments.
7. Establish Accounting and Bookkeeping Processes
Accounting should be organised from the beginning of business operations, rather than postponed until the first tax deadline approaches.
Accurate financial records help the company monitor cash flow, understand profitability, substantiate expenses, and prepare required tax filings.
Set up your accounting system
Start by establishing a reliable process for:
- Recording income and expenses.
- Issuing invoices and maintaining sales records.
- Recording supplier invoices and receipts.
- Reconciling bank transactions.
- Tracking receivables and payables.
- Recording payroll and employee expenses where applicable.
- Maintaining asset and liability records.
- Preparing management reports.
- Supporting tax calculations and financial statements.
- Retaining financial documentation for the required period.
Choose an accounting method and system that fit the company’s transaction volume and reporting needs.
Even a small business should have a clear process for recording transactions and retaining supporting evidence.
Separate personal and business finances
Avoid mixing personal spending with company transactions without appropriate documentation and accounting treatment.
Use the company’s business account for legitimate business transactions once available, and maintain clear evidence for funds introduced by owners or paid out to them.
This separation makes reconciliation easier and can help when responding to bank, tax, or financial due diligence requests.
For support with financial recordkeeping, explore SmartBiz’s accounting and bookkeeping services in Dubai.
8. Put Employment and Payroll Procedures in Place
If the company intends to hire employees, it should establish the relevant employment, work permit, payroll, and immigration procedures before employees begin working.
Requirements depend on the company’s jurisdiction, the worker’s circumstances, and the applicable employment framework.
Employment readiness checklist
- Confirm the correct hiring and work permit procedure.
- Prepare the required employment contract.
- Complete relevant work permit and residence visa procedures.
- Establish payroll and salary payment arrangements.
- Assess applicable Wage Protection System requirements.
- Check health insurance obligations.
- Maintain employee records.
- Track visa and work permit expiry dates.
- Establish procedures for leave, attendance, and other relevant employment records.
Do not assume that every free zone and mainland employer follows identical administrative procedures.
Check the requirements of the relevant labour, free zone, and immigration authorities before hiring.
If the company has no employees, some of these tasks may not be immediately relevant. They should still be considered before the first hire.
9. Review UBO and Corporate Recordkeeping Requirements
Company owners should check whether the applicable beneficial ownership framework requires the business to identify beneficial owners, maintain prescribed registers, or submit information to its competent registrar.
These obligations depend on the entity’s legal form, applicable legislation, and any relevant exclusions.
What to review?
- Current shareholder and ownership information.
- Beneficial owner identification where required.
- Direct and indirect ownership arrangements.
- Manager and authorised representative details.
- Required company registers.
- Relevant updates following ownership or control changes.
- Applicable filing procedures and deadlines.
Under the relevant UAE beneficial ownership framework, applicable entities must maintain and update covered information in accordance with the prescribed requirements.
Do not treat beneficial ownership documentation as a one-time incorporation task. Ownership or control changes may trigger additional review and reporting obligations.
For further information, read the guide on Ultimate Beneficial Owner (UBO) in the UAE.
10. Review AML Compliance Requirements for Your Business
Not every UAE company has the same AML obligations.
Financial institutions and certain designated non-financial businesses and professions may have specific anti-money laundering and counter-terrorist financing responsibilities under the applicable framework.
Businesses should determine whether their activities bring them within a regulated category.
Where applicable, compliance procedures may cover:
- Risk assessment.
- Customer identification and due diligence.
- Beneficial ownership checks.
- Enhanced due diligence for higher-risk relationships.
- Ongoing monitoring.
- Recordkeeping.
- Suspicious transaction reporting.
- Employee training and internal controls.
- Relevant registration and reporting procedures.
A newly formed company should identify these requirements early if its activities fall within the relevant framework.
For more detail, see SmartBiz’s guide to AML Compliance in the UAE.
11. Organise Contracts, Suppliers, and Operational Systems
Once the core registration and compliance tasks are underway, the business should establish the systems required to operate reliably.
The specific requirements depend on the company’s business model.
Operational setup checklist
- Prepare standard customer contracts and terms of service.
- Review supplier and service provider agreements.
- Establish an invoicing and payment collection process.
- Set up business email and document management.
- Create a process for tracking customer enquiries and sales.
- Establish secure storage for company documents.
- Review appropriate business insurance.
- Assess data protection and confidentiality requirements.
- Set up inventory or project management systems where needed.
- Create a process for monitoring expenses and cash flow.
Contracts should clearly define the parties, scope of work, payment terms, responsibilities, and other relevant commercial conditions.
Where contracts involve regulated activities, significant financial commitments, or complex ownership arrangements, consider obtaining appropriate professional advice.
12. Create a Compliance Calendar for Your New Company
A compliance calendar helps business owners track upcoming deadlines and avoid relying on memory.
The calendar should reflect the company’s actual obligations. Some items recur monthly or quarterly, others annually, and some are triggered by specific events.
| Timing | Items to consider | What to check |
|---|---|---|
| At incorporation | Company documents and licensed activities | Accuracy of registration records |
| Before commencing relevant activities | Additional approvals and premises conditions | Whether the business is authorised to operate |
| Before hiring | Employment and immigration procedures | Work permits, contracts, and applicable approvals |
| When required | Corporate Tax and VAT registration | Applicable status and deadlines |
| Monthly or periodically | Bookkeeping and bank reconciliation | Complete and accurate financial records |
| Assigned tax period | VAT return and payment, where applicable | The company’s actual filing schedule |
| Tax-period based | Corporate Tax return and payment | Applicable tax period and filing deadline |
| On relevant changes | Ownership, licence, manager, or premises updates | Whether a formal amendment or filing is required |
| Before expiry | Trade licence, visas, permits, and insurance | Renewal requirements and lead times |
This is a planning framework rather than a universal legal timetable. Add confirmed dates from the relevant authorities and assign responsibility for each item.
13. Common Mistakes to Avoid After Company Formation
Assuming the trade licence completes every requirement
A licence is an important milestone, but tax registration, immigration, banking, and other obligations may remain.
Delaying tax assessments
Waiting until the first return is due can make it harder to establish accurate records or meet a registration deadline.
Applying for a bank account without preparation
Incomplete ownership information, unclear business activities, and missing supporting documents may lead to further questions or delays.
Ignoring accounting from the beginning
Reconstructing several months of transactions later can be time-consuming and may leave gaps in supporting evidence.
Overlooking employment procedures
Employers should confirm the required permits, contracts, and immigration steps before onboarding staff.
Failing to monitor renewals
Trade licences, visas, permits, and other records may have different expiry dates. Each should be tracked separately.
Assuming every company has identical obligations
Requirements can differ between mainland companies, free zones, regulated activities, and individual tax situations.
Post-Incorporation Checklist for UAE Businesses
Use this practical checklist to review your company’s next steps.
- Collect and verify incorporation documents and the trade licence.
- Confirm the approved activities and any additional operational approvals.
- Check establishment and immigration requirements.
- Prepare a corporate bank account application.
- Assess Corporate Tax registration obligations.
- Assess VAT registration requirements.
- Set up bookkeeping and accounting procedures.
- Establish invoicing and payment collection processes.
- Arrange employment and payroll procedures if hiring.
- Review beneficial ownership and corporate register requirements.
- Assess applicable AML obligations.
- Organise contracts and supplier documentation.
- Review insurance and sector-specific requirements.
- Create a compliance calendar with assigned responsibilities.
- Retain evidence of registrations, filings, payments, and approvals.
Frequently Asked Questions About What to Do After Company Formation in the UAE
1. What should I do immediately after receiving a UAE trade licence?
Start by checking the licence and incorporation documents for accuracy. Then identify the next steps applicable to your business, including banking, immigration, tax registration, accounting, and any additional operational approvals.
2. Can I open a corporate bank account immediately after company formation?
You can generally begin the bank’s application process once you have the required documentation, but approval is not guaranteed. Each bank applies its own due diligence and onboarding requirements.
3. Do I need to register for Corporate Tax after company formation?
You should assess your company’s Corporate Tax status and applicable registration requirements. The obligation and deadline depend on the relevant rules and the company’s circumstances.
4. Does every newly formed UAE company need VAT registration?
No. VAT registration depends on the applicable registration rules, taxable supplies, imports, and relevant thresholds or special circumstances.
5. Do I need a UAE residence visa after setting up a company?
Company ownership and residence visa eligibility are separate matters. The available visa route and requirements depend on the applicant, company structure, and applicable immigration procedures.
6. Should I start bookkeeping as soon as the company is formed?
Yes. Establishing a bookkeeping process early helps the company maintain reliable records, track cash flow, substantiate expenses, and prepare for applicable tax and reporting obligations.
7. Does a free zone company have the same compliance requirements as a mainland company?
Not necessarily. Requirements vary according to the registration authority, business activity, tax status, and other circumstances. Companies should confirm the rules that apply to their specific setup.
8. When should I review UBO requirements?
Review the applicable beneficial ownership requirements during the initial compliance assessment and whenever relevant ownership or control information changes. The specific obligations depend on the entity and applicable framework.
9. What happens if I delay my post-incorporation tasks?
Depending on the obligation, delays may result in missed filing deadlines, administrative problems, additional costs, or other consequences. The impact depends on the applicable requirement and circumstances.
10. What is the best way to manage post-incorporation compliance?
Maintain a central checklist, assign responsibility for each obligation, record confirmed deadlines, retain supporting evidence, and review the process whenever the business changes.
Conclusion
Understanding what to do after company formation in the UAE helps business owners move from registration to operational readiness in a more organised way.
The main priorities are to verify company documents, confirm licensing conditions, assess immigration and banking requirements, determine tax obligations, establish accounting procedures, and create a reliable compliance calendar.
Not every company follows the same process or timeline. Business owners should prioritise the steps that apply to their legal structure, activities, workforce, and registration authority.
By addressing these responsibilities early, businesses can build a stronger operational foundation and reduce avoidable administrative problems as they grow.
For guidance on establishing a company and organising the relevant setup process, explore SmartBiz’s business setup services in Dubai.
Disclaimer: This article provides general educational information and is not legal, tax, or immigration advice. UAE requirements and administrative procedures may change. Confirm the current obligations with the relevant authority or a qualified professional before taking action.