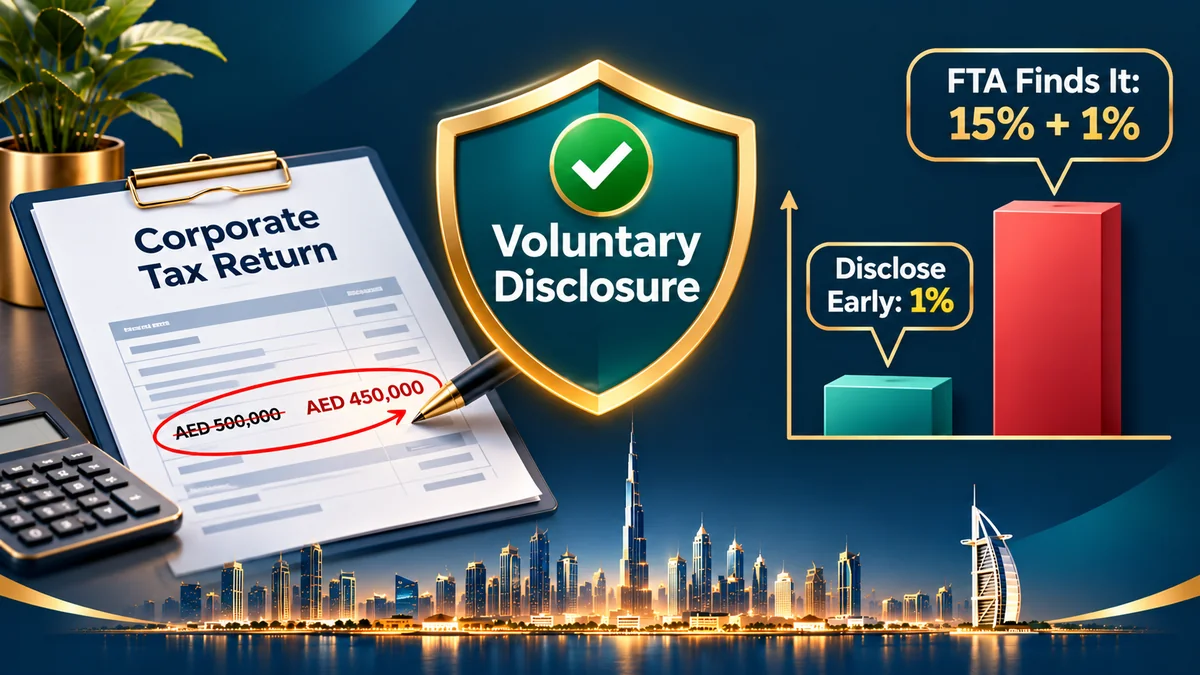
Quick Answer: A corporate tax voluntary disclosure in the UAE is the formal way to correct an error in a Corporate Tax return you have already filed with the Federal Tax Authority (FTA). It is submitted through EmaraTax. It is mandatory when the error means you paid too little tax, and optional when you paid too much. If you disclose before the FTA notifies you of an audit, the penalty is generally 1% of the tax difference for each month since the original due date. If the FTA finds the error first, the penalty rises to a 15% fixed penalty plus 1% per month. Disclosures can generally be made within 5 years from the end of the relevant tax period.
Mistakes in a Corporate Tax return are more common than most business owners expect. A missed adjustment, a misclassified expense, an incorrect exempt income figure or a wrongly applied relief can all change the tax you owe. The question is not whether errors happen, but how quickly and correctly you fix them.
This guide explains the FTA voluntary disclosure rules for Corporate Tax: what a voluntary disclosure is, when it is required, how penalties are calculated, how to file one on EmaraTax and which records you need to support it.
Corporate Tax Voluntary Disclosure UAE: Key Numbers at a Glance
| Figure | What it means |
|---|---|
| 1% per month | Penalty on the tax difference when you disclose before an FTA audit notice |
| 15% + 1% per month | Penalty when the FTA discovers the error, or you disclose only after an audit notice |
| 5 years | General time limit to submit a voluntary disclosure from the end of the tax period |
| 20 business days | Timeframe under the Tax Procedures rules to disclose after becoming aware of an error |
| 14% per year | Late payment penalty on Corporate Tax not paid by its due date |
| 9 months | Deadline to file the Corporate Tax return after the tax period ends; the penalty clock starts from here |
What Is a Voluntary Disclosure in UAE Corporate Tax?
A voluntary disclosure is a form submitted to the FTA to notify it of an error or omission in a tax return, tax assessment or refund application that you have already submitted. The legal basis is Article 10 of the Tax Procedures Law (Federal Decree-Law No. 28 of 2022, as amended by Federal Decree-Law No. 17 of 2025). The related penalties are set by Cabinet Decision No. 75 of 2023 on Corporate Tax administrative penalties.
The idea is simple: the UAE system rewards businesses that correct their own mistakes before the FTA finds them. A self-reported error attracts a much smaller penalty than one uncovered during an FTA audit.
Key distinction: A voluntary disclosure corrects your own return. If you disagree with a decision the FTA has made, such as a tax assessment or a penalty, the route is a reconsideration request, not a voluntary disclosure.
When Is a Corporate Tax Voluntary Disclosure Required?
Mandatory disclosure
You must submit a UAE tax voluntary disclosure when an error in a filed Corporate Tax return or refund application results in:
- Less Corporate Tax paid than was actually due (an underpayment), or
- A refund claimed that was higher than the amount you were entitled to.
Optional disclosure
You may submit a voluntary disclosure when the error results in:
- More Corporate Tax paid than was due (an overpayment), or
- A refund claimed that was lower than your entitlement.
In these cases, the disclosure is how you recover the overpaid amount, as a refund or as a credit against future liabilities.
Visual: Do you need to file a voluntary disclosure?
| Situation | Disclosure required? | Why |
|---|---|---|
| Taxable income under-reported, tax underpaid | ✔ Mandatory | Payable tax was understated |
| Non-deductible expense claimed as deductible | ✔ Mandatory | Taxable income and tax were understated |
| Exempt income overstated | ✔ Mandatory | Taxable income was understated |
| Small Business Relief or a QFZP 0% rate applied wrongly | ✔ Mandatory | Tax due was understated |
| Deductible expense missed, tax overpaid | Optional | Correct it to recover the overpayment |
| Error spotted before the return due date | Usually not | Correct the return itself before the due date, where EmaraTax allows |
| Disagreement with an FTA assessment or penalty | ✘ Not this route | Use an FTA reconsideration request |
Recent change: Under the amendments made by Federal Decree-Law No. 17 of 2025, the FTA can specify which corrections must go through a voluntary disclosure and which can be made by submitting a corrected tax return. Always check the current FTA guidance and the options shown on EmaraTax for your case.
Common Errors That Lead to a Corporate Tax Voluntary Disclosure
These are the mistakes that most often require a tax return error correction in the UAE:
| Error type | Example |
|---|---|
| Non-deductible expenses | Entertainment expenses deducted in full instead of the permitted 50% |
| Connected person payments | Owner-director salary deducted above market value |
| Interest limitation | Net interest expense above the permitted limit not added back |
| Exempt income | Dividends or capital gains treated as exempt without meeting the conditions |
| Reliefs and elections | Small Business Relief claimed when revenue exceeded the threshold |
| Free zone treatment | Non-qualifying income taxed at 0% by a Qualifying Free Zone Person |
| Transfer pricing | Related-party transactions not adjusted to arm’s length values |
| Tax losses | Losses carried forward or offset incorrectly |
| Accounting errors | Year-end adjustments, accruals or depreciation recorded incorrectly |
| Data entry | Wrong figures typed into the EmaraTax return |
Voluntary Disclosure Penalties: How Much Will It Cost?
The voluntary disclosure penalty for Corporate Tax depends mainly on timing: whether you disclose before or after the FTA contacts you.
| Scenario | Fixed penalty | Monthly penalty |
|---|---|---|
| Disclosure before any FTA audit notice | None | 1% of the tax difference per month (or part month) from the return due date until the disclosure is submitted |
| Disclosure after an FTA audit notice | 15% of the tax difference | 1% per month |
| No disclosure; FTA finds the error | 15% of the tax difference | 1% per month until the FTA assessment |
If the error results in no tax difference, the percentage-based penalty is effectively zero. However, the correction should still be made.
Worked example: AED 100,000 underpayment found 8 months after the due date
| Option | Fixed penalty | Monthly penalty (1% × 8 months) | Total penalty |
|---|---|---|---|
| Proactive voluntary disclosure | AED 0 | AED 8,000 | AED 8,000 |
| FTA discovers the error in an audit | AED 15,000 | AED 8,000 | AED 23,000 |
The cost of waiting: In this example, letting the FTA find the error costs almost three times more than disclosing it yourself. And every extra month of delay adds another 1% to the bill.
Visual: How the penalty grows with delay (AED 100,000 tax difference)
| Months after due date | Proactive disclosure | FTA discovers the error |
|---|---|---|
| 3 months | AED 3,000 | AED 18,000 |
| 6 months | AED 6,000 | AED 21,000 |
| 12 months | AED 12,000 | AED 27,000 |
| 24 months | AED 24,000 | AED 39,000 |
On top of these penalties, any tax still unpaid can attract a late payment penalty of 14% per year. This is why the additional tax should be paid at the same time as the disclosure is submitted.
Voluntary Disclosure Time Limits in the UAE
There are two time rules to keep in mind:
- Act promptly once you know. Under the Tax Procedures rules, a taxpayer who becomes aware of an error should submit the voluntary disclosure within 20 business days. Separately, the 1% monthly penalty keeps running until you file.
- The five-year outer limit. Under the amended Tax Procedures Law, a voluntary disclosure can generally be submitted within 5 years from the end of the relevant tax period. The FTA’s general audit and assessment window is also five years, with some exceptions.
Once an audit notice arrives, the window closes. After the FTA notifies you of a tax audit, you lose the benefit of the lower proactive penalty for errors in the audited period.
How to Correct a Corporate Tax Return in the UAE: Step by Step
Here is how to correct a Corporate Tax return in the UAE through a voluntary disclosure:
- Identify the error and its cause. Pin down exactly what went wrong: a wrong figure, a misapplied rule or a missed adjustment.
- Recalculate the tax position. Prepare the corrected taxable income and tax payable, and work out the tax difference (original vs correct).
- Gather supporting documents. Collect revised ledgers, invoices, contracts, calculations and workings that prove the corrected figures.
- Log in to EmaraTax. Open the Corporate Tax section for the relevant taxable person and select the voluntary disclosure option for the affected tax period.
- Enter the original and corrected figures. EmaraTax shows the original return values. Enter the corrected amounts so the system calculates the difference.
- Explain the error. Give a short, factual explanation of what happened and why. Avoid vague statements.
- Upload documents and submit. Attach the supporting evidence and submit the disclosure.
- Pay the additional tax. Settle the tax difference promptly to avoid late payment penalties. Penalties are typically raised separately by the FTA.
Need to correct a second time? If a disclosure itself contains an error, you can submit a further disclosure. The penalty is still measured from the original due date.
What Documents Support a Voluntary Disclosure?
| Document | Why it matters |
|---|---|
| Original Corporate Tax return | Shows the figures being corrected |
| Corrected tax computation | Shows how the new taxable income and tax were calculated |
| Revised financial statements or adjusting entries | Supports accounting-based corrections |
| Invoices, contracts and agreements | Proves the nature of income or expenses |
| Transfer pricing workings | Supports arm’s length adjustments for related-party or connected-person transactions |
| Relief and election evidence | Supports SBR, QFZP or exemption claims, or explains why they no longer apply |
| Written explanation | Gives the FTA a clear, consistent account of the error |
Strong records are the foundation of any correction. If your books are not reliable, the same errors will keep coming back. Professional accounting and bookkeeping services help prevent repeat disclosures.
Can You Recover Overpaid Corporate Tax Through a Voluntary Disclosure?
Yes. If you discover you overpaid Corporate Tax, you can submit a voluntary disclosure to correct the return. The resulting credit can be:
- Refunded to your bank account through a refund request, or
- Kept as a credit and used against future tax liabilities.
Under the amended Tax Procedures Law, refund requests and the use of credits are generally subject to a 5-year time limit from the end of the relevant tax period. Overpayments should therefore be corrected without delay.
Voluntary Disclosure for Corporate Tax vs VAT
Many businesses already know voluntary disclosures from VAT. The concept is the same, but some details differ:
| Point | Corporate Tax | VAT |
|---|---|---|
| Return frequency | Annual | Quarterly or monthly |
| Penalty rules | Cabinet Decision No. 75 of 2023 | Cabinet Decision No. 129 of 2025 |
| Proactive disclosure penalty | 1% per month on the tax difference | 1% per month on the tax difference |
| Penalty if FTA finds the error first | 15% + 1% per month | 15% + 1% per month |
| Small-error correction in next return | Not generally available (annual return) | Available for certain smaller VAT differences |
If you also need to correct VAT returns, our VAT filing services cover VAT voluntary disclosures.
Common Mistakes When Filing a Voluntary Disclosure
- Waiting to “see if the FTA notices”. If it does, the penalty jumps from 1% per month to 15% plus 1% per month.
- Not paying the tax difference with the disclosure. Unpaid tax can attract additional late payment penalties.
- Fixing the symptom, not the cause. If the underlying accounting error is not fixed, the same mistake appears in next year’s return.
- Weak explanations. Vague narratives invite FTA questions. Be specific and factual.
- No supporting documents. A disclosure without evidence is hard to accept.
- Using a voluntary disclosure to dispute an FTA decision. That requires a reconsideration request instead.
- Forgetting knock-on effects. A correction in one year can affect losses carried forward, transfer pricing positions or tax group figures in later years.
Voluntary Disclosure Checklist
| Step | Done? |
|---|---|
| Error identified and root cause documented | ☐ |
| Corrected tax computation prepared and reviewed | ☐ |
| Tax difference calculated | ☐ |
| Supporting documents collected | ☐ |
| Clear written explanation drafted | ☐ |
| Voluntary disclosure submitted on EmaraTax | ☐ |
| Additional tax paid | ☐ |
| Impact on later years (losses, TP, groups) reviewed | ☐ |
| Accounting process fixed to prevent repeats | ☐ |
How SmartBiz Helps With Corporate Tax Corrections
Finding an error in a filed return is stressful, but fixing it correctly is manageable. SmartBiz supports UAE businesses with:
- Accounting and bookkeeping in Dubai: clean records that reduce errors and support corrections
- VAT filing and VAT registration: including VAT voluntary disclosures
- Business setup in Dubai and company formation in the UAE, with tax compliance planned from day one
- Business PRO services for government-facing processes
- A single point of contact through our business services hub in Dubai
Found an error in your Corporate Tax return?
SmartBiz helps you assess the error, prepare the corrected computation and submit your voluntary disclosure before penalties grow. Book a Consultation
Frequently Asked Questions
What is a corporate tax voluntary disclosure in the UAE?
It is a form submitted to the FTA through EmaraTax to correct an error or omission in a Corporate Tax return, assessment or refund application that has already been submitted.
When is a voluntary disclosure mandatory for UAE Corporate Tax?
It is mandatory when an error results in less Corporate Tax being paid than was due, or a higher refund being claimed than was allowed. It is optional when the error results in an overpayment.
What is the penalty for a voluntary disclosure in UAE Corporate Tax?
If you disclose before an FTA audit notice, the penalty is generally 1% of the tax difference for each month from the original due date. If the FTA finds the error first, the penalty is 15% of the tax difference plus 1% per month.
How long do I have to submit a voluntary disclosure in the UAE?
Under the Tax Procedures rules, you should disclose within 20 business days of becoming aware of the error. Voluntary disclosures can generally be submitted within 5 years from the end of the relevant tax period.
Can I amend my Corporate Tax return instead of filing a voluntary disclosure?
Errors identified before the return due date can usually be corrected in the return itself, where EmaraTax allows it. After the due date, corrections are generally made through a voluntary disclosure or another route specified by the FTA.
Can I submit a voluntary disclosure after receiving an FTA audit notice?
You can still correct the error, but you lose the lower proactive penalty treatment. A 15% fixed penalty plus 1% per month can apply.
Can I get back overpaid Corporate Tax through a voluntary disclosure?
Yes. A voluntary disclosure can correct an overpayment, and the resulting credit can be refunded or used against future tax liabilities, subject to the 5-year time limit.
What is the difference between a voluntary disclosure and a reconsideration request?
A voluntary disclosure corrects your own return. A reconsideration request challenges a decision made by the FTA, such as a tax assessment or penalty.
Sources and Legal References
- Federal Decree-Law No. 28 of 2022 on Tax Procedures: Article 10 (Voluntary Disclosure)
- Federal Decree-Law No. 17 of 2025 amending the Tax Procedures Law
- Cabinet Decision No. 75 of 2023 on Administrative Penalties for Violations Related to the Application of Corporate Tax
- Cabinet Decision No. 129 of 2025 on Administrative Penalties for VAT and Excise Tax violations
- Federal Decree-Law No. 47 of 2022 on the Taxation of Corporations and Businesses
- Federal Tax Authority: tax.gov.ae
Disclaimer: This article provides general information based on UAE tax legislation and FTA guidance available at the time of writing. It is not tax or legal advice. Penalty rules and FTA procedures can change, so confirm your specific position with a qualified tax adviser before submitting a disclosure.